Business-owning families often carry more complexity than they realize. Their responsibilities may include operating companies, private wealth, investments, trusts, real estate, philanthropy, succession plans, and relationships across several generations.
Family office management brings these responsibilities into one coordinated system. This framework serves ultra-high-net-worth families and those with growing business or investment responsibilities. It helps organize decisions, advisors, records, responsibilities, and values so private wealth serves a lasting purpose. For Christian families, this work is also an expression of stewardship, wisdom, integrity, and care for those who will inherit leadership.
Key Takeaways
Family office management is broader than both wealth management and investment management. It coordinates the financial, legal, operational, relational, and long-term needs of a family enterprise.
A formal office isn’t necessary for every family. However, as assets, entities, advisors, and family members increase, coordinating financial planning with legal, operational, and relational needs becomes more valuable.
A family office works best when it protects both the family’s resources and the relationships required to steward them well.
What Is Family Office Management and Why Does My Family Need It?
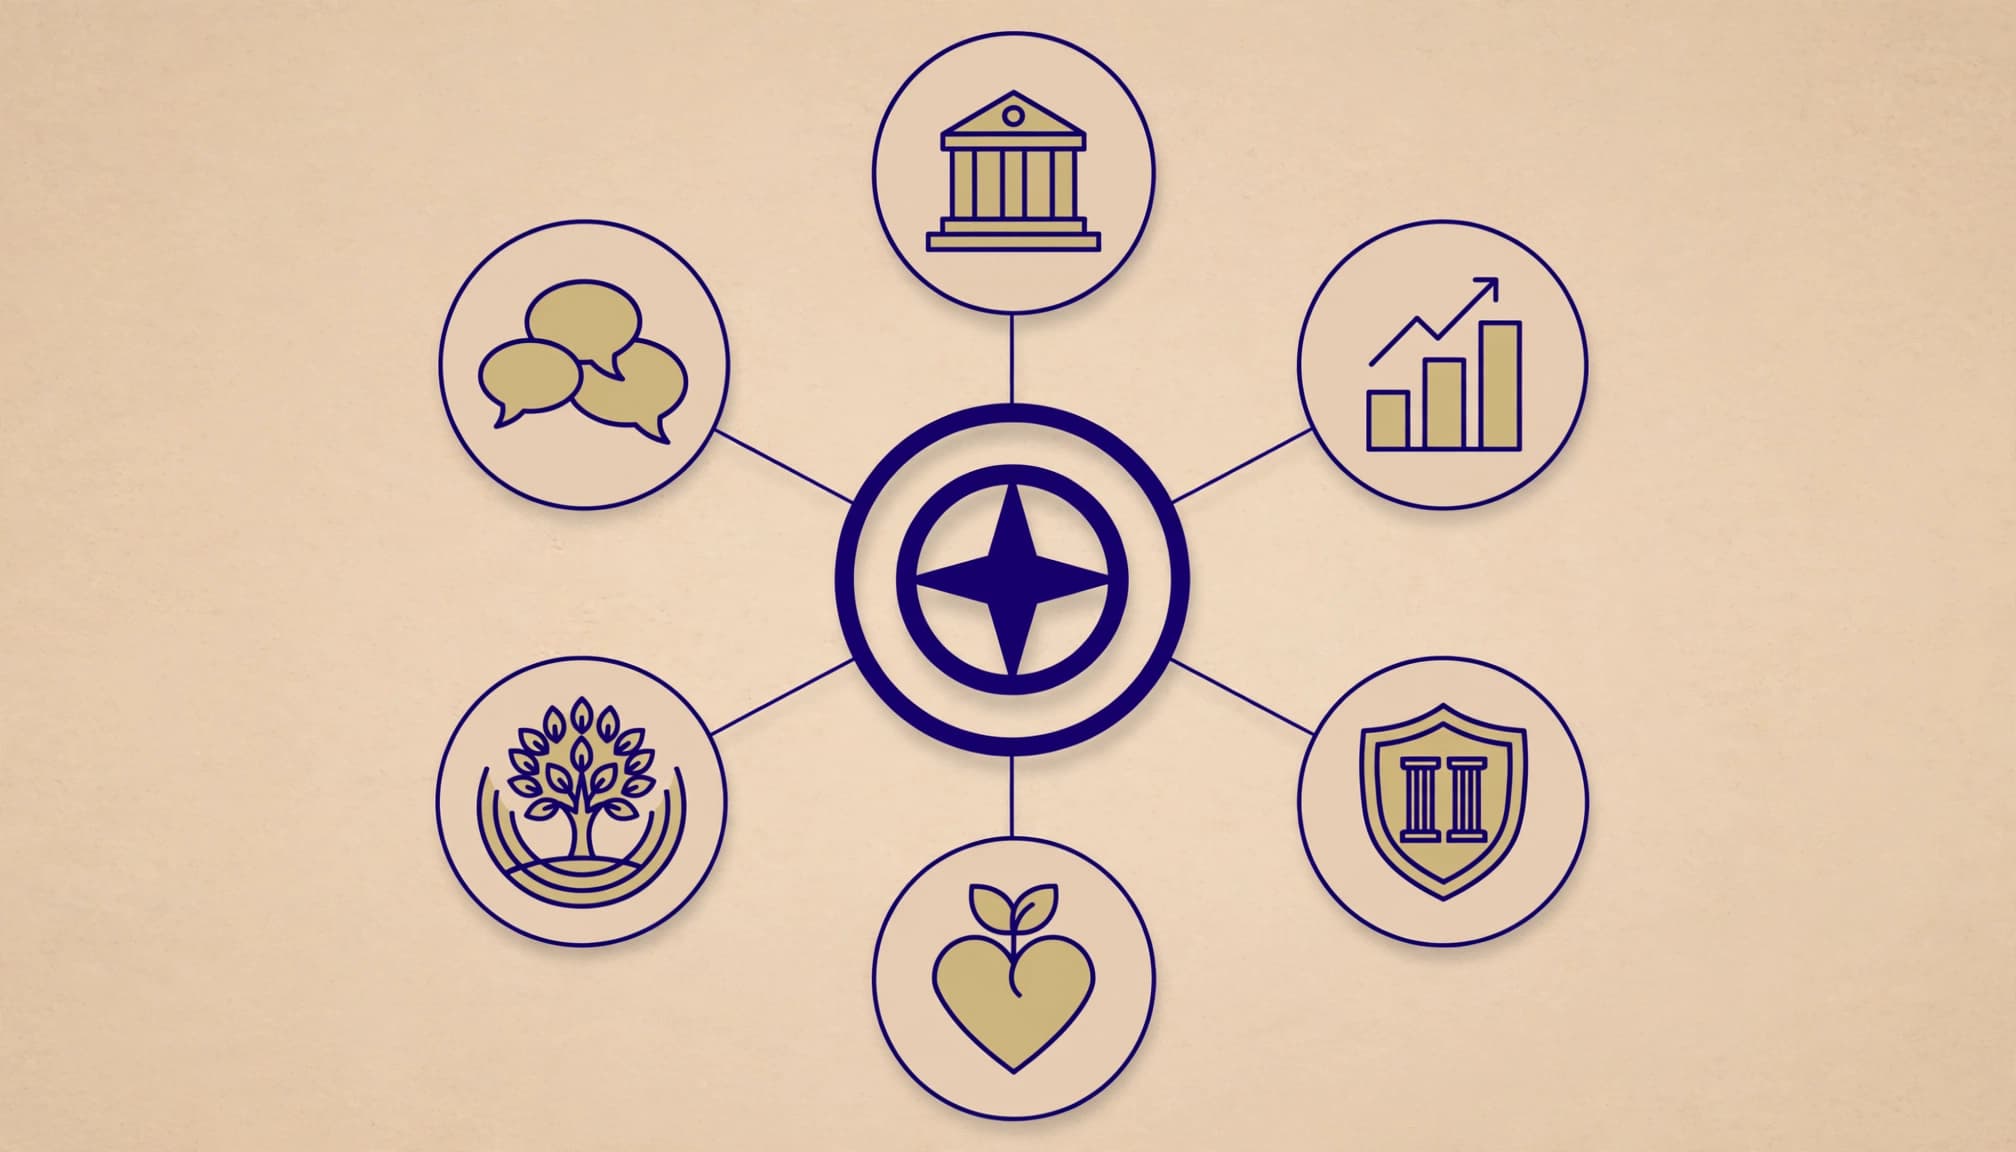
Family office management is the organized oversight of a family’s financial affairs, business interests, estate planning, trust administration, tax planning, legal affairs, records, advisors, governance, and long-range priorities. Its purpose is to bring order to areas that often develop separately over decades.
A family office manager or managing director coordinates financial planning, financial advisory, risk management, and portfolio management. That person may also oversee asset and entity mapping, reporting, due diligence, document control, governance support, and succession coordination.
This role does not replace attorneys, CPAs, investment advisers, insurance professionals, or trustees. Instead, the manager creates a reliable process through which those specialists can work with accurate information and clear direction.
The Difference Between Managing Wealth and Managing the Family Enterprise
Wealth management usually focuses on investment management, portfolio design, risk tolerance, and financial priorities. Those services matter, yet they address only part of a business-owning family’s responsibilities.
Family office management considers the wider family enterprise. It may connect a family’s net worth, closely held business, operating LLCs, trusts, insurance policies, investment accounts, philanthropy management, and lifestyle management. The Centre for Family Enterprise describes this broader perspective in its family-enterprise framework, which considers both meaningful family activities and financial interests.
For example, a family may have one attorney handling trusts, a CPA preparing returns, a business executive running operations, and adult children who lack a shared view of the plan. A coordinated office can maintain an entity map, schedule decisions, document action items, and identify which advisor owns each task.
What a Well-Run Family Office Helps the Family Do
A well-run system gives family members a dependable view of what they own, who is responsible, and what decisions require attention. It also reduces duplicated requests for documents and prevents important details from living only in one person’s memory.
The goal is not control for its own sake. The goal is clarity, continuity, and responsible stewardship. Strong processes support wealth preservation, protect confidential information, clarify duties, and prepare rising family members for greater responsibility.
When communication improves, relatives can spend less time resolving avoidable confusion. They can give greater attention to shared values, charitable purpose, and the health of the family itself.
How Family Office Management Protects Continuity Across Generations
Continuity becomes difficult when ownership, leadership, wealth, and family responsibilities move at different speeds. Financial planning must account for changing ownership, while wealth transfer and wealth preservation depend on clear leadership responsibilities. A founder may still lead the business while trusts have already named beneficiaries and younger relatives are beginning to participate in family decisions.
Succession is not a single document signed during a crisis. It is an ongoing practice of preparing people, documenting systems, reviewing plans, and building trust over time. A coordinated family office can connect these responsibilities across generations. London Business School groups wealth management, governance, and succession planning together in its family office leadership curriculum, a connection that reflects the reality facing complex families.
Governance, Family Meetings, and Clear Decision Rights
Family governance gives relatives a structured way to discuss matters that affect them collectively. Depending on the family, governance may include a family council, an annual assembly, an ownership committee, a philanthropy committee, or regular family meetings.
Written roles and decision rights reduce uncertainty. A meeting agenda should identify the purpose of the discussion, the information required, the people authorized to decide, and the next actions. Minutes, confidentiality expectations, and follow-up dates make these meetings more useful.
Family meetings should also create a respectful setting for difficult subjects. Ownership expectations, conflict, compensation, family employment, charitable priorities, and leadership transitions all require honest conversation. Clear procedures help families address these matters before personal frustration becomes a larger dispute.
Preparing Rising Generations for Leadership and Stewardship
The next generation needs more than technical knowledge about investments or business operations. Members need gradual responsibility, practical financial education, mentoring, communication skills, and a clear understanding of accountability.
Preparing the next generation for leadership should include readiness assessments that identify strengths and developmental needs. These assessments shouldn’t assume that every descendant should hold the same role. One family member may become an operating executive, while another may contribute as a board member, trustee, philanthropist, or informed owner.
For Christian families, stewardship also involves character. Humility, service, truthfulness, wise use of authority, and concern for others should shape leadership formation. Families from different denominational traditions may apply these principles differently, but a shared commitment to faithful responsibility can guide the process.
Bank of Singapore’s discussion of succession planning amid family-enterprise complexity reinforces a practical point: succession planning must adapt as family structures and financial arrangements become more sophisticated.
Which Family Office Model Fits Your Family’s Needs?
Families commonly use one of three models. A single-family office serves one family and offers the greatest direct control over staff, processes, and privacy. However, it usually requires greater administrative effort and direct expense.
A multi-family office serves several families. It may offer access to shared specialists, established reporting systems, and a broader professional network. The tradeoff is less direct control over every operational choice.
A virtual family office coordinates a distributed network of advisors, technology, and internal family leadership. It can fit families with significant complexity that don’t need or want a fully staffed physical office.
When a Virtual Family Office May Be the Practical Starting Point
A virtual family office may use a secure document environment, customer relationship management system, workflow tools, reporting processes, and scheduled advisor coordination. Its success depends on disciplined administration, not technology alone.
Each document needs an owner, access level, retention standard, and review cycle. Likewise, every task should have a named person responsible for completion. Cybersecurity, regulatory compliance, multi-factor authentication, secure backups, limited permissions, and documented processes are basic requirements.
Technology can make information easier to find, but it can’t supply judgment or repair broken trust. Families still need qualified advice, careful review, and direct communication.
The Costs, Benefits, and Tradeoffs to Consider
Costs may include staff compensation, technology subscriptions, legal and tax advice, cybersecurity, reporting, governance support, and administrative services. A dedicated office generally creates higher direct costs, while a multi-family office or virtual arrangement may distribute some expenses.
In return, families may gain stronger visibility, better records, clearer accountability, and fewer preventable errors. Investment management and asset allocation may also need to account for alternative assets, including private equity and direct investments. Families may protect private wealth information more effectively and improve coordination among advisors.
A thoughtful comparison looks beyond the price of the system. It also considers the potential cost of unmanaged risk, missed deadlines, undocumented decisions, fragmented information, or an unprepared successor. Academic literature continues to examine how family offices contribute to family businesses, as shown in this systematic review of family office research.
How to Build a Family Office Management Plan
Families should begin with a focused assessment rather than trying to solve every issue at once. Start by identifying where confusion, delay, risk, or family tension already exists.
A practical plan usually follows this sequence:
- Identify family goals, values, and immediate pain points.
- Create an inventory of assets, entities, insurance, trusts, operating businesses, and charitable commitments. Include ownership records, beneficiary information, and wealth transfer plans.
- Map current advisors, their responsibilities, and the information they need. Assign clear owners for financial planning and financial advisory work.
- Review legal, operational, cybersecurity, regulatory compliance, and continuity risks with qualified professionals.
- Define governance needs, reporting schedules, meeting rhythms, and measurable next steps.
Education helps family leaders understand both technical systems and human dynamics. Students and advisors seeking structured training in leadership, communication, and stewardship can Learn More About Family Office.
Start With a Focused Assessment
An asset and entity inventory often reveals gaps that no one intended to create. Families may find outdated beneficiary information, undocumented loans, unclear ownership records, duplicate accounts, or key documents stored in several locations.
A useful assessment also identifies decision bottlenecks. If every issue depends on one senior family member, the family has a continuity risk. If no one tracks advisor recommendations, important work may remain incomplete.
The first planning document doesn’t need to be perfect. It needs to identify the current state, assign responsibility, and establish a review date.
Questions to Ask Before Hiring a Family Office Manager
The right manager combines organizational discipline with sound judgment and emotional intelligence. The person must work comfortably with family members, employees, and outside professionals while maintaining strict confidentiality.
Consider these questions during the selection process:
- Has the candidate worked with complex family enterprises, entities, trusts, and multiple advisors?
- How does the candidate protect confidential records and manage access to digital information?
- Can the candidate explain reporting methods, meeting rhythms, and escalation procedures in plain language?
- How does the candidate coordinate investment management with attorneys, CPAs, trustees, and other advisers while respecting professional boundaries?
- Does the candidate have a calm, service-centered approach to conflict and family communication?
- Will references confirm reliability, discretion, follow-through, and alignment with the family’s values?
A capable manager doesn’t make every decision. Instead, that person creates the conditions for informed decisions and consistent execution.
Frequently Asked Questions
What does family office management include?
Family office management coordinates a family’s financial affairs, business interests, trusts, estate planning, tax planning, legal matters, records, advisors, governance, and long-term priorities. It creates a structured process for managing responsibilities that may otherwise remain fragmented.
Does every family need a formal family office?
No. A formal office isn’t necessary for every family, but coordination becomes more valuable as assets, entities, advisors, and family responsibilities increase. Some families may use a dedicated office, while others may choose a multi-family office or virtual arrangement.
What is the difference between wealth management and family office management?
Wealth management generally focuses on investments, portfolio design, risk tolerance, and financial priorities. Family office management takes a broader view by connecting wealth management with business interests, trusts, governance, succession, philanthropy, records, and family relationships.
How does family office management support succession planning?
It connects ownership records, leadership responsibilities, governance, education, and communication across generations. This helps families prepare future leaders, document important decisions, and address changes before succession becomes an urgent problem.
A Coordinated Framework for Faithful Stewardship
Family office management provides a practical framework for protecting assets, strengthening relationships, preparing future leaders, and carrying a family’s purpose forward. Families don’t need extraordinary wealth to benefit from better organization, although increased complexity raises the value of a formal system.
The work begins with an honest assessment of current responsibilities, risks, and relationships. Wise stewardship supports wealth preservation and responsible wealth transfer while equipping the next generation with clearer responsibilities, stronger values, and a better foundation for serving others.